Blockchain
 Crypto Mining
 Cryptocurrency
 DAO
 DeFi
 Decentralized Exchanges
 Financial Services
 Fintech
 SPACs
 Web3
 AI
 App Developers
 Cloud Computing
 Education Technology
 Esports
 Influencers
 IoT
 MSPs
 Media & Advertising
 Podcasters
 Robotics
 SaaS
 Social Media
 Startups
 Technology
 TikTok Creators
 Virtual Reality
 YouTubers
 Biotech
 Cleantech
 Clinical Trials
 Dietary Supplement & Nutraceutical
 FamTech & BabyTech
 HealthTech
 Life Science Risk Management
 Pharmaceutical
 Advertising Agencies
 Amazon Seller
 Direct-to-Consumer Brands
 Ecommerce
 Financial Services
 PR Agencies
 Professional Services
 Publishers
 Shopify Stores
 info@foundershield.com
 28 Liberty Street, New York, NY 10005
 646.854.1058


Carl Niedbala
Managing Partner; COO & Co-Founder
Key Takeaways
Managing Partner; COO & Co-Founder
Plenty of situations cause us to reexamine our lives. Consider graduations, job promotions, weddings, child’s birth, etc. In business, some events can prompt a reexamining type of scenario, too. When it comes to your risk management plan, specific situations encourage business owners to take a mindful pause and reevaluate their professional positioning in the industry. In this post, we identify five of those events.
What’s a Risk Management Plan?
Professional vulnerabilities and exposures are around every bend in the river. No matter how secure or stable a specific market, unpredictability is always a threat. As a result, most companies have established what’s known as a risk management plan.
This documented plan typically pinpoints valid risks the company could face, ways to avoid them, and how to recover from a vulnerable situation if one occurs. Risk management plans often include these four elements regarding handling exposures:
- Assessment
- Analysis
- Tolerance
- Mitigation
Resilience is a theme that weaves through many risk management plans. After all, recovery is a significant part of staying a professional course. Naturally, savvy leaders search for ways to avoid particular situations altogether. As a result, insurance coverage plays a vital role in establishing a robust plan.
The primary headache with developing an excellent risk management plan boils down to merely doing it. However, this “nose to the grindstone” approach typically involves some trigger, such as specific happenings. Let’s look at these events.
When to Review Your Risk Management Plan
Like major personal life events, the following professional occurrences encourage business owners to review the risk management plan.
1. Significant Revenue Growth
Companies that experience a boom in business face different risks than they did before the rapid development. Significant revenue growth serves as a trigger to reexamine your business’s vulnerabilities because they’ve likely changed during the growing season.
Expansion is typically a positive occurrence — but it does change things. For example, insurance carriers want to know about your company size, funding status, and annual revenue, among other details. This information will probably change your premium, as well as your overall coverage.
Reviewing your insurance policy once a year is standard. However, experiencing significant revenue growth is a reason to review your risk management plan before the regular coverage renewal.
2. Increase in Workforce
In addition to experiencing an uptick in revenue growth, you might have increased your workforce, too. Having a focused and positive workforce on your side is exciting. No doubt that your company will profit from hiring such a great team.
But more people means more potential employee-related issues surfacing. A new wave of employees should prompt you to reevaluate your workers’ compensation and employment practices liability (EPL) insurance.
Most states require workers’ compensation insurance. It covers employee’s medical expenses and lost wages if they’re injured on the job. EPL insurance covers your company if you have to pay to defend against any lawsuits from employees. Often, these allegations include:
- Harassment
- Discrimination
- Retaliation
- Wrongful termination
As you might have imagined, these lawsuits can skyrocket to immense amounts in a flash. Having the appropriate employee coverage included in your risk management plan will help to keep your business successful in the long run.
3. Massive Loss or Damage
There’s no way around it; Mother Nature is relentless and ruthless. Furthermore, no one can honestly predict when a natural disaster will occur. When a catastrophe does strike, it can be devastating to its victims, including your company.
From office space to inventory to costly equipment, many items could end up needing replacing. Unfortunately, replacement costs have shuttered plenty of businesses. Avoiding the burden of recovering from massive loss means investing in the correct amount of property insurance.
Property insurance is an indemnity policy that works to reimburse a company for direct losses it experiences. Without this coverage, you’re left to cover the price of replacing or repairing your physical property. It’s not ideal, but encountering a loss or damage causes many businesses to reexamine their property insurance policy.
4. Upon Renewal
Few executives genuinely enjoy insurance renewal time. It’s an added responsibility and can often seem daunting. However, business insurance renewals aren’t as dreadful as many believe them to be. For example, Founder Shield has an effortless process when it comes to renewals; it’s painless.
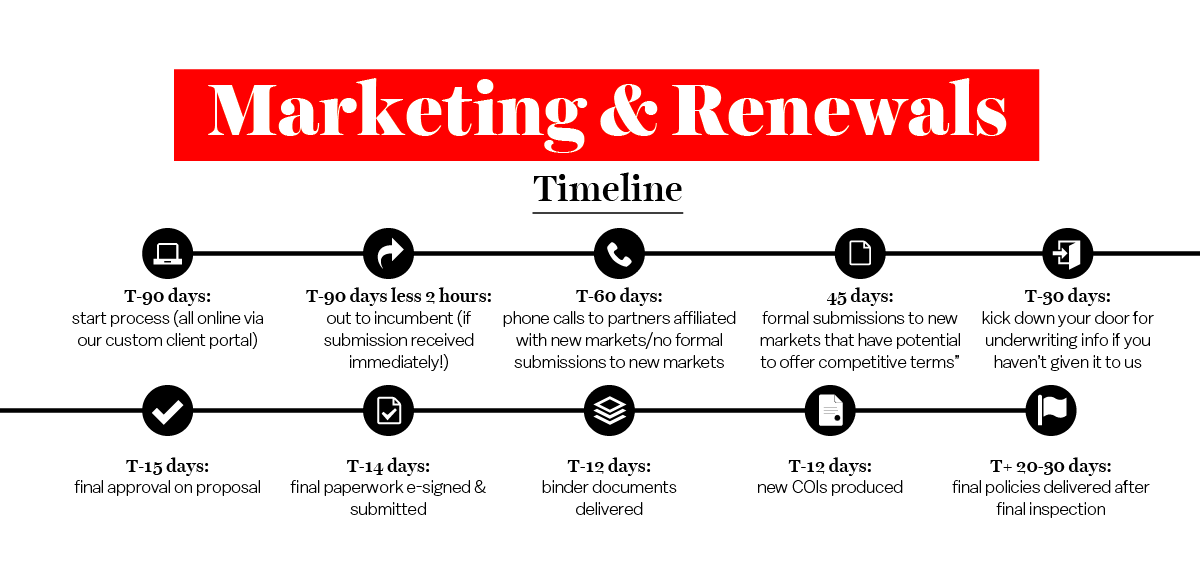
The most natural and effortless way to review your current business insurance is during your annual renewal time frame. During this time, you already have all the necessary information available at your fingertips. So, making adjustments isn’t incredibly burdensome.
5. Before Funding Rounds
No matter if your company is launching a Seed Round, Series A, Series B, or another campaign altogether, it’s the perfect time to take another look at your risk management plan. Besides, most venture capital (VC) investors require at least directors and officers (D&O) insurance before signing the dotted line for a deal.
An investment firm wants to protect its investment by minimizing exposure and safeguarding its board members. For this reason, they will more readily invest in companies with adequate insurance coverage.
Our in-depth Series A guide on how to raise venture capital details the vital steps your company needs to take to secure funding. Before you dive into a funding round, be sure to reexamine the current insurance policies supporting your risk management plan. Then, make changes to support expansion.
Understanding the details of what coverage your company needs can be a confusing process. Founder Shield specializes in knowing the risks your industry faces to make sure you have adequate protection. Feel free to reach out to us, and we’ll walk you through the process of finding the right policy for you.
Want to know more about small business insurance? Talk to us! You can contact us at info@foundershield.com or create an account here to get started on a quote.